Everyone tells you your credit score matters for a mortgage. Nobody shows you exactly how much. Here's what 40 points is actually worth: on a $350,000 conventional loan with 5% down, moving from a 700 to a 740 FICO score can save you $165–$190 per month between rate improvements and PMI reductions. Over a typical 5-year ownership period, that's $9,900–$11,400 — from a score change that can happen in two weeks with the right strategy.
Let's break down exactly where those savings come from.
How Credit Score Affects Your Mortgage Rate
Mortgage rates aren't one-size-fits-all. Lenders use loan-level pricing adjustments (LLPAs) — essentially surcharges or discounts based on your risk profile. Credit score is the biggest factor in those adjustments.
Here's what rate tiers typically look like (these are relative, not absolute — actual rates depend on market conditions):
FICO Score RangeTypical Rate AdjustmentRate on a 6.75% Base760+Best pricing — no adjustment6.75%740–759+0.125%6.875%720–739+0.25%7.00%700–719+0.375% – 0.50%7.125% – 7.25%680–699+0.625% – 0.75%7.375% – 7.50%660–679+1.00% – 1.25%7.75% – 8.00%640–659+1.50%+8.25%+620–639+2.00%+ or denial8.75%+
What this means in dollars on a $350,000, 30-year fixed loan:
FICORateMonthly Payment (P&I)Monthly Savings vs. 7007406.875%$2,298$50/month saved7207.00%$2,329$19/month saved7007.25%$2,348— baseline —6807.50%$2,447$99/month MORE6607.75%$2,508$160/month MORE
The gap between 660 and 740 is roughly $210/month in principal and interest alone. Over 30 years, that's $75,600. Over 5 years (a more typical ownership period), it's $12,600.
Altgage Perspective: These are representative ranges based on publicly available LLPA data. Your actual rate depends on loan type, property type, down payment, and market conditions. As a broker, Altgage shops multiple lenders to find the best pricing for your specific credit tier — rate differences between lenders can be as large as the differences between score tiers. Check your personalized rate at rates.altgage.com.
How Credit Score Affects PMI Cost
This is where the math gets dramatic — and where most borrowers are completely in the dark.
Private mortgage insurance (PMI) is required on conventional loans with less than 20% down. But PMI isn't a flat rate — it's priced on a grid of credit score × loan-to-value ratio (LTV). And credit score is the dominant driver.
Using standard MGIC/Radian rate card data, here's what PMI looks like at 95% LTV (5% down) on a $400,000 loan:
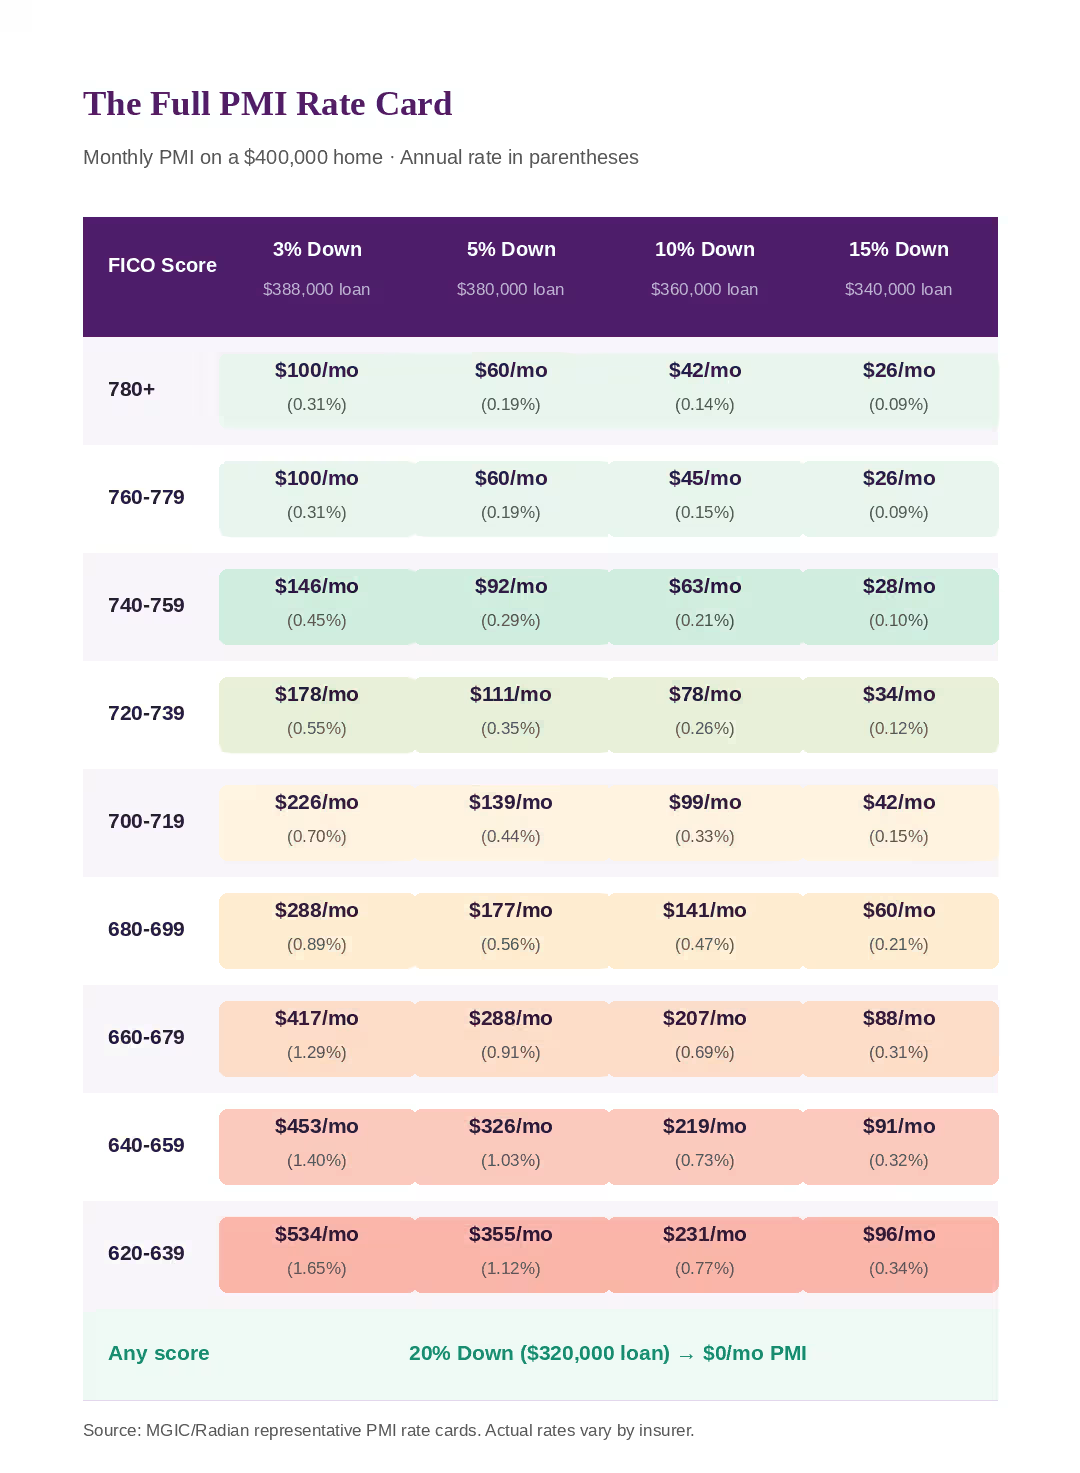
The credit score swing on PMI is massive. A borrower at 620 pays $355/month in PMI. A borrower at 760+ pays $60/month. That's a $295/month difference — nearly $3,600 per year — driven entirely by credit score.
More practically, the jump from 680 to 740 saves $85/month on PMI alone. Combined with the rate savings above, that 40-point improvement is worth $164/month — and that's on a modest $380,000 loan. On a $500,000 loan, scale everything up proportionally.
For a deeper dive on PMI costs by credit score and down payment, read How Much Is PMI?
The Key Insight: Credit Score Impacts PMI 2-4× More Than Down Payment
Here's something that surprises nearly every borrower we work with: your credit score affects PMI cost roughly 4 times more than your down payment percentage.
To illustrate: take a borrower at 680 FICO. If they increase their down payment from 5% to 10% (an enormous cash outlay — $20,000 extra on a $400,000 home), their PMI drops by roughly $36/month.
Now take that same borrower and boost their score from 680 to 740 — zero additional cash needed. Their PMI drops by $85/month.
The score improvement costs nothing upfront and delivers more than double the monthly savings. This is why we push credit optimization before down payment optimization for borrowers in the 680–740 range.
ChangeCash RequiredMonthly PMI SavingsDown payment: 5% → 10% $20K~$36/monthCredit score: 680 → 740 $0~$85/monthScore impact is 2.4× the savings for $0 cost
At the extremes of the rate card, credit score swings PMI by $295/month (620 to 760+) while LTV column shifts change PMI by $124/month (95% to 90%).
The Combined Savings: Rate + PMI
Here's the full picture for a $350,000 loan at 95% LTV:
FICOMonthly Rate CostMonthly PMITotal MonthlySavings vs. 700740$2,298$93$2,391$164/month720$2,329$134$2,463$92/month700$2,348$207$2,555— baseline —680$2,447$254$2,701+$146/month660$2,508$321$2,829+$274/month
Over 5 years:
FICO JumpMonthly Savings5-Year Savings700 → 740$164$9,840680 → 740$310$18,600660 → 740$438$26,280
These numbers don't include the lifetime interest savings on the lower rate — over 30 years, the 700 → 740 jump saves approximately $36,000 in interest and PMI combined. The 660 → 740 jump saves over $90,000.
When FHA Makes the Score Math Different
Everything above applies to conventional loans. For borrowers with credit scores below 700, FHA loans change the calculus.
FHA mortgage insurance works differently: it's a flat 0.55% annual MIP regardless of your credit score (for the standard 30-year, >95% LTV product). On a $350,000 loan, that's roughly $160/month — the same whether your score is 580 or 740.
This means that for borrowers in the 620–680 range, FHA is often cheaper than conventional because of the conventional PMI surcharge at lower scores:
FICOConventional PMIFHA MIPWinner740+$93/mo$160/moConventional720$134/mo$160/moConventional700$207/mo$160/moFHA680$254/mo$160/moFHA660$321/mo$160/moFHA
The crossover point is around 710–720 FICO — above that, conventional is cheaper. Below it, FHA typically wins on monthly cost (though FHA MIP doesn't cancel like PMI does, so the long-term math can differ).
This is exactly why a credit boost from 700 to 740 is so impactful — it flips the equation from "FHA is your better option" to "conventional with low PMI saves you significantly."
What a Rapid Credit Boost Is Worth
Altgage's Rapid Credit Boost program typically delivers 20–100 point improvements in about two weeks, at no cost to the borrower. Here's what that translates to for three common scenarios:
Scenario 1: First-time buyer, 705 → 742 (+37 points)
- Rate savings: ~$50/month
- PMI savings: ~$114/month
- Total: $164/month saved / $9,840 over 5 years
Scenario 2: Self-employed buyer, 678 → 722 (+44 points)
- Rate savings: ~$100/month
- PMI savings: ~$120/month
- Total: $220/month saved / $13,200 over 5 years
Scenario 3: Investor (DSCR loan), 665 → 710 (+45 points)
- Rate savings: ~$125/month (DSCR rates are higher but follow similar tiering)
- Down payment reduction: 25% → 20% (saves $17,500 in upfront capital)
- Total: $125/month saved + $17,500 freed up for the next property
In every scenario, a free service that takes two weeks generates five-figure savings. That's why we offer it to every borrower who comes through our pipeline.
The Bottom Line
Your credit score doesn't just decide whether you get approved — it determines how much you pay every single month. The math is unambiguous: a 40-point improvement from 700 to 740 saves roughly $164/month on a $350,000 loan, translating to nearly $10,000 over 5 years and $36,000+ over the life of the loan. For most borrowers, credit optimization is the single highest-ROI action in the entire mortgage process. It costs nothing, takes weeks instead of months, and the savings compound for as long as you hold the loan. If your score has room to improve, Altgage's Rapid Credit Boost program can help you get there — free, with an 80%+ success rate. Check live rates at rates.altgage.com, or get pre-approved.
Frequently Asked Questions
Does 1 point on my credit score actually matter?
Individual points don't — but crossing a tier threshold does. Credit scores are priced in bands (typically 20-point ranges). Going from 738 to 739 changes nothing. Going from 739 to 740 crosses into the next tier and can save you $100+ per month.
What's the ideal credit score for a mortgage?
For conventional loans, 740+ gets you the best available rates and lowest PMI. Above 760, the improvement is marginal. Below 740, every 20-point drop costs real money.
Does credit score affect VA and USDA loans the same way?
VA and USDA loans don't have PMI, so the PMI savings don't apply. However, your credit score still affects your interest rate through LLPAs. VA loans have their own funding fee that varies by down payment and service history, but rate adjustments by credit score are similar.
Should I improve my credit score or save for a bigger down payment?
If you're in the 680–740 FICO range with less than 20% down, improving your score almost always delivers more monthly savings per dollar of effort than increasing your down payment. The exception is if you're very close to 20% down (which eliminates PMI entirely).
How accurate are these numbers?
The rate adjustments are based on publicly available LLPA data from Fannie Mae/Freddie Mac. PMI costs are from standard MGIC/Radian rate cards. Actual numbers vary by lender, loan program, property type, and market conditions. Use rates.altgage.com for current, personalized pricing.
Related Reading on Altgage
- How to Boost Your Credit Score for a Mortgage (Fast) — The full Rapid Credit Boost guide
- 5 Fastest Ways to Boost Your Credit Score Before a Mortgage
- How Much Is PMI? — PMI costs by credit score and down payment
- How Much Does a Rapid Rescore Improve Credit?
- What Is a Rapid Rescore? Can I Do It Myself?
- Get Your Rate →
- Get Pre-Approved →