Boost Your Credit Score
The smart way to lower mortgage rates
6 credit scores: FICO & VantageScore 4.0
Best case pricing, automatically
Free FICO credit boosts
700
Excellent
300
850
650
Equifax
680
Experian
720
TransUnion
670
Equifax
700
Experian
720
TransUnion
FICO Scores
Vantage Scores 4.0
Scores pulled from 6 different sources, not just the standard 3
Take advantage of
The Vantage advantage
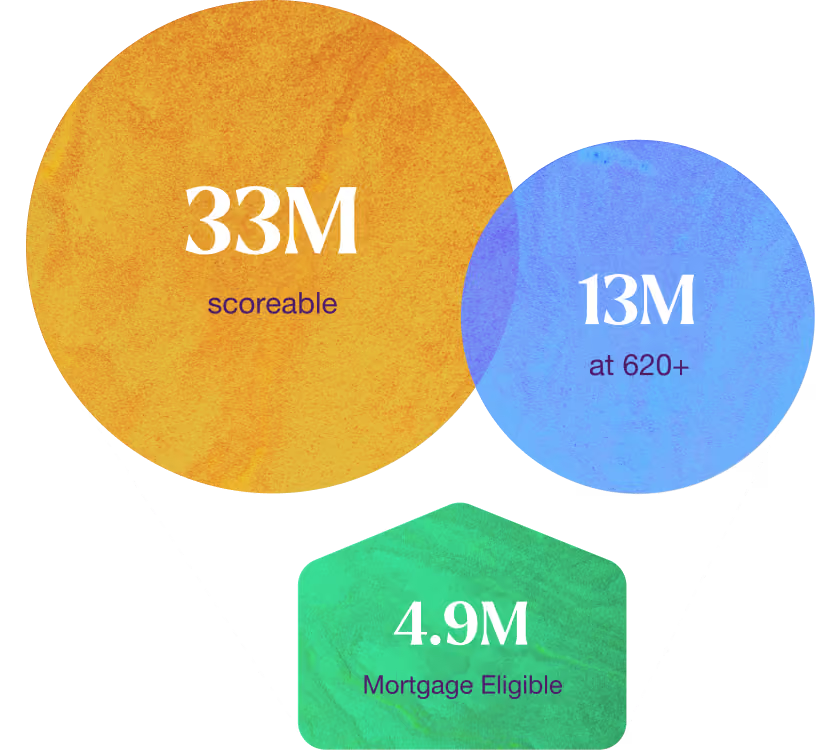
4.9M more qualified
- Scores thin credit files that FICO can't
- Fannie Mae and Freddie Mac now accept VantageScore 4.0
- We pull both, so one model doesn't decide for you
VantageScore estimates 4.9 million more people could qualify for a mortgage (620+ score, ages 25–65). Applies to conventional loans sold to Fannie Mae and Freddie Mac. FHA and VA loans still use FICO.
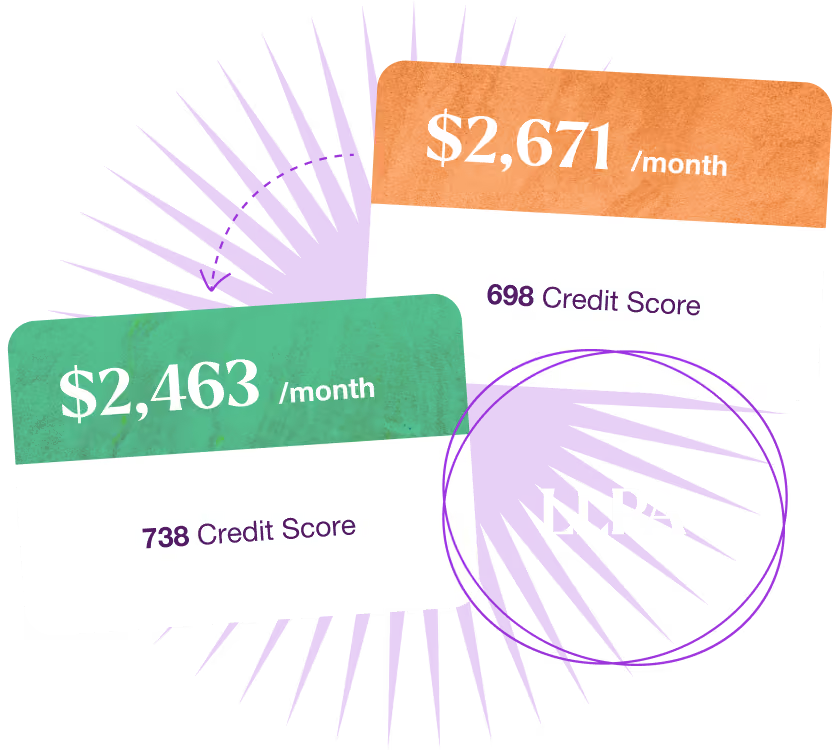
Lower rate
- Conventional loan pricing is tied to your credit score
- We price your loan on your higher score
- A higher score can move you into a better pricing tier
Your rate depends on your full credit profile, loan type, and lender pricing. See today's rates at rates.altgage.com.
Lower PMI
- PMI cost depends on your credit score and down payment
- A higher score can lower your monthly PMI
- You can ask to remove PMI once you reach 20% equity
PMI applies to conventional loans with less than 20% down. Each mortgage insurer sets its own rates and score rules.
Higher budget
- A lower rate and PMI shrink your monthly payment
- The same payment can buy a more expensive home
- Your pre-approval reflects your best score
Your budget also depends on income, debts, and down payment. Educational example only, not a commitment to lend.
The Altgage credit boost
Boost your FICO score in 5 steps
When Vantage is lower, we can boost your FICO with our 5-step rapid rescore:
1
We do a hard pull of your credit history
2
Run the simulation with credit expert
3
Send official
balance letters
4
Rescored
in ~7 days
5
Pay down cards, adjust authorized users, negotiate pay-for-deletes, fix errors
A hard pull is your friend
Make the best trade
MYTH: A hard pull will tank my score.
REALITY: It costs about 5 points — and they come back within a few months. A rounding error next to a lower rate you'll hold for 30 years.
MYTH: Checking a few lenders stacks up the damage.
REALITY: FICO counts every mortgage inquiry in a 45-day window as one. Shop as hard as you like — it's a single hit.
MYTH: A soft-pull prequalification is enough to see where I stand.
REALITY: A soft pull shows one score — and can't move it. Only a hard tri-merge pull reveals all six (three FICO, three VantageScore), the real numbers underwriting uses — and it's the only pull that can rescore your FICO. Without it, we're flying blind.
MYTH: The smart move is to protect my score and keep it untouched.
REALITY: A credit score has one job — getting you a home. A spotless score you never use to buy anything is worth exactly nothing.
Frequently asked questions
You’ve got questions, we’ve got answers
It depends on the loan. FHA allows scores as low as 580 with 3.5% down, and most conventional loans need at least 620. Higher scores get you better rates and lower PMI.
A rapid rescore asks the credit bureaus to update your report after you pay down a balance or fix an error. Your score can update in days instead of waiting for the next monthly report. Only a lender can request one.
Very little. Mortgage credit checks made within a short shopping window count as a single inquiry in credit scoring, so you can compare lenders without repeated hits.
For conventional loans sold to Fannie Mae and Freddie Mac, lenders can now use VantageScore 4.0. FHA and VA loans still use FICO. We check both and price your loan on your higher score.
Paying credit card balances down below 30% of their limits, and correcting errors on your report, usually have the biggest effect. A rapid rescore then gets the higher score on record quickly.
Related articles
Related articles
Related articles
Related articles

Boost my credit
Today's rates
